Last Updated: October 8, 2026
When someone hits your car, you file a car insurance claim with either your own insurer or the at-fault driver's insurer, and that choice shapes everything that follows. Total-loss frequency hit 23.1% of claims, a new industry high, according to [CCC Intelligent Solutions' Crash Course 2026 Report](https://www.cccis.com/reports/crash-course-2026). The same report found average paid bodily-injury claim severity rose 10.3% year over year. Those numbers matter because they show insurers are paying more per claim, and they fight harder over fault.
At Cummings Law Car Accident & Personal Injury Lawyers, we advocate for victims across Middle Tennessee. Below, we break down both claim routes, the timeline, and what to do when the other driver stalls or lies.
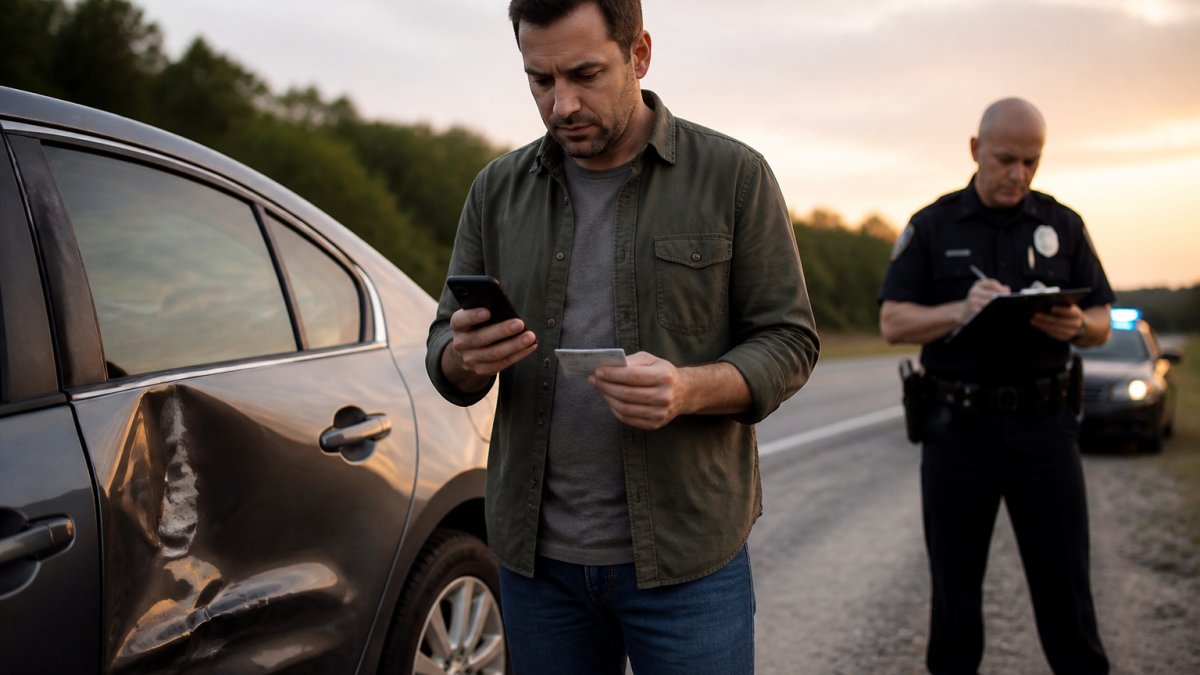
A first-party claim goes through your own policy. A third-party claim goes through the other driver's policy.
That single distinction decides your deductible, your wait time, and who negotiates for you.
The catch most people miss: your insurer has a duty to you. The other driver's insurer does not. It answers to its own policyholder.
| Factor | First-Party Claim | Third-Party Claim |
|---|---|---|
| Who you file with | Your insurer | At-fault driver's insurer |
| Deductible | You pay it upfront | None |
| Repair speed | Usually faster | Often delayed |
| Fault disputes | Handled by your insurer | You handle them |
| Risk to premiums | Possible increase | No effect on your policy |
Most claims move through six stages, and knowing them helps you spot delays early.
A typical timeline runs from a few weeks to several months. Injury claims take longer than property damage claims.
File with your own insurer if the other driver is uninsured, underinsured, fleeing the scene, or disputing fault. Your policy is the faster, more reliable route in those cases.
Here is when filing first-party makes sense:
Filing with your own insurer is not an admission of fault. It is a contract benefit you already pay for.
Now the honest downside. A first-party claim can raise your premium, depending on your policy terms and your state's rules. A third-party claim through the at-fault driver's policy usually will not touch your rates.
A hit-and-run or a parking lot strike follows the same basic steps as any crash, minus the other driver.
Do this in order:
If the driver left, your uninsured motorist coverage or collision coverage typically pays for vehicle repairs. You still owe your deductible unless your policy states otherwise.
A hit-and-run insurance claim runs through your own policy, usually under uninsured motorist coverage or collision coverage. That is the key difference from a standard crash: there is no other insurer to pursue, so your own policy is the only route unless the driver is later identified. (Source: National Highway Traffic Safety Administration (NHTSA) data)
Which coverage pays depends on your policy and your state's rules:
If you do not have UM or collision coverage, you may have no first-party route for the vehicle damage, which is why the police report and any evidence of the other driver matter so much.
The police report is the backbone of this claim. Insurers want proof that you reported the accident and that the other driver truly left. Without it, the claim gets scrutinized harder, and some insurers will deny a hit-and-run claim that was never reported.
Gather everything you can:
A common pattern is that the insurer asks for a recorded statement and a proof-of-loss form. Read the form carefully, answer only what is asked, and keep a copy. If the insurer denies the claim, ask for the denial in writing and cite the specific policy language it relied on.
State law matters here. Most states require drivers to stop and exchange information after a crash, and leaving the scene can carry criminal penalties. Reporting rules and claim deadlines vary, so check your state's requirements for how quickly a crash must be reported and how long you have to file a claim.
If the driver is later identified, the claim can shift. Your insurer may pursue the at-fault driver or their insurer for reimbursement, and you may be able to pursue a third-party claim for injuries and out-of-pocket costs. A lawyer can help you preserve evidence, deal with the adjuster, and press for compensation if the insurer undervalues the claim.
A car insurance claim usually takes two to six weeks for property damage and several months for injury claims. The clock starts when you file and depends on how fast fault is settled.
Speed depends on four things:
Total-loss claims take longer because the insurer must value the vehicle, and you can challenge a low offer. Injury claims take longest because treatment and medical records take time to complete.
When the other driver disputes fault or goes silent, stop negotiating with them directly and let the evidence and your insurer carry the claim.
Do these three things:
A disputed-fault claim often comes down to evidence quality. A police report that names the other driver as at fault carries real weight. So do photos, skid marks, and witness accounts.
If the other insurer denies your claim, you have options: appeal the denial, file through your own collision coverage, or pursue the at-fault driver directly. A claim denial is not the end of the road.
This is where a lawyer changes the math. Cummings Law operates on a contingency fee basis, so you pay no fees unless we win. We have recovered over $47,000,000.00 for clients, and we negotiate directly with insurers so you are not fighting a claims adjuster alone. If you are in Middle Tennessee and the other driver has gone quiet, the Tennessee Department of Safety & Homeland Security keeps the crash report process and reporting rules you will need.
A disputed claim, a silent driver, or a lowball offer can leave you covering repair costs, medical bills, and lost wages on your own. Cummings Law Car Accident & Personal Injury Lawyers fights these battles every day, with no upfront cost and no fee unless we win. We protect your rights under Tennessee law, negotiate with the insurance companies, and pursue compensation for your medical expenses, lost wages, and property damage. Get started with Cummings Law and let us take the claim fight off your plate.
You can file with your own insurer or the at-fault driver's insurer. Filing with your own carrier under collision coverage typically gets your car repaired faster, but you pay your deductible upfront and your insurer may seek reimbursement from the other driver later. Filing with the at-fault driver's insurer avoids your deductible but often takes longer and depends on their cooperation. The right choice depends on fault, coverage, and how quickly you need your vehicle back.
If the at-fault driver is uninsured or flees, your uninsured motorist coverage and collision coverage become the primary options. Uninsured motorist coverage is designed for exactly this situation and may cover injuries and property damage. For a hit-and-run, report the accident to police as soon as possible and file a hit-and-run insurance claim with your own insurer. Documentation from the scene, including photos and witness information, strengthens your claim.
Timelines vary widely based on fault disputes, coverage limits, and investigation complexity. A straightforward claim with clear fault and cooperative insurers may resolve in a few weeks. Claims involving disputed liability, uninsured drivers, or total-loss valuations can take months. Under Tennessee law, you generally have one year from the date of a personal injury accident to file a lawsuit, so consult an attorney if your claim stalls.
Yes, but you need repair authorization from the insurer first. If you use your own collision coverage, your insurer typically pays the shop directly minus your deductible. If you wait for the at-fault driver's insurer, they must approve the repair estimate before work begins. Getting repairs done without authorization risks the insurer denying or reducing reimbursement. Keep all estimates, photos, and receipts to support your claim.

Cummings Law Car Accident & Personal Injury Lawyers Address: 4235 Hillsboro Pike #300, Nashville, TN 37215